Payment Processing
How to Choose a Payment Processor for Your Business
By Adara Group Team · Published October 6, 2026 · 5 min read
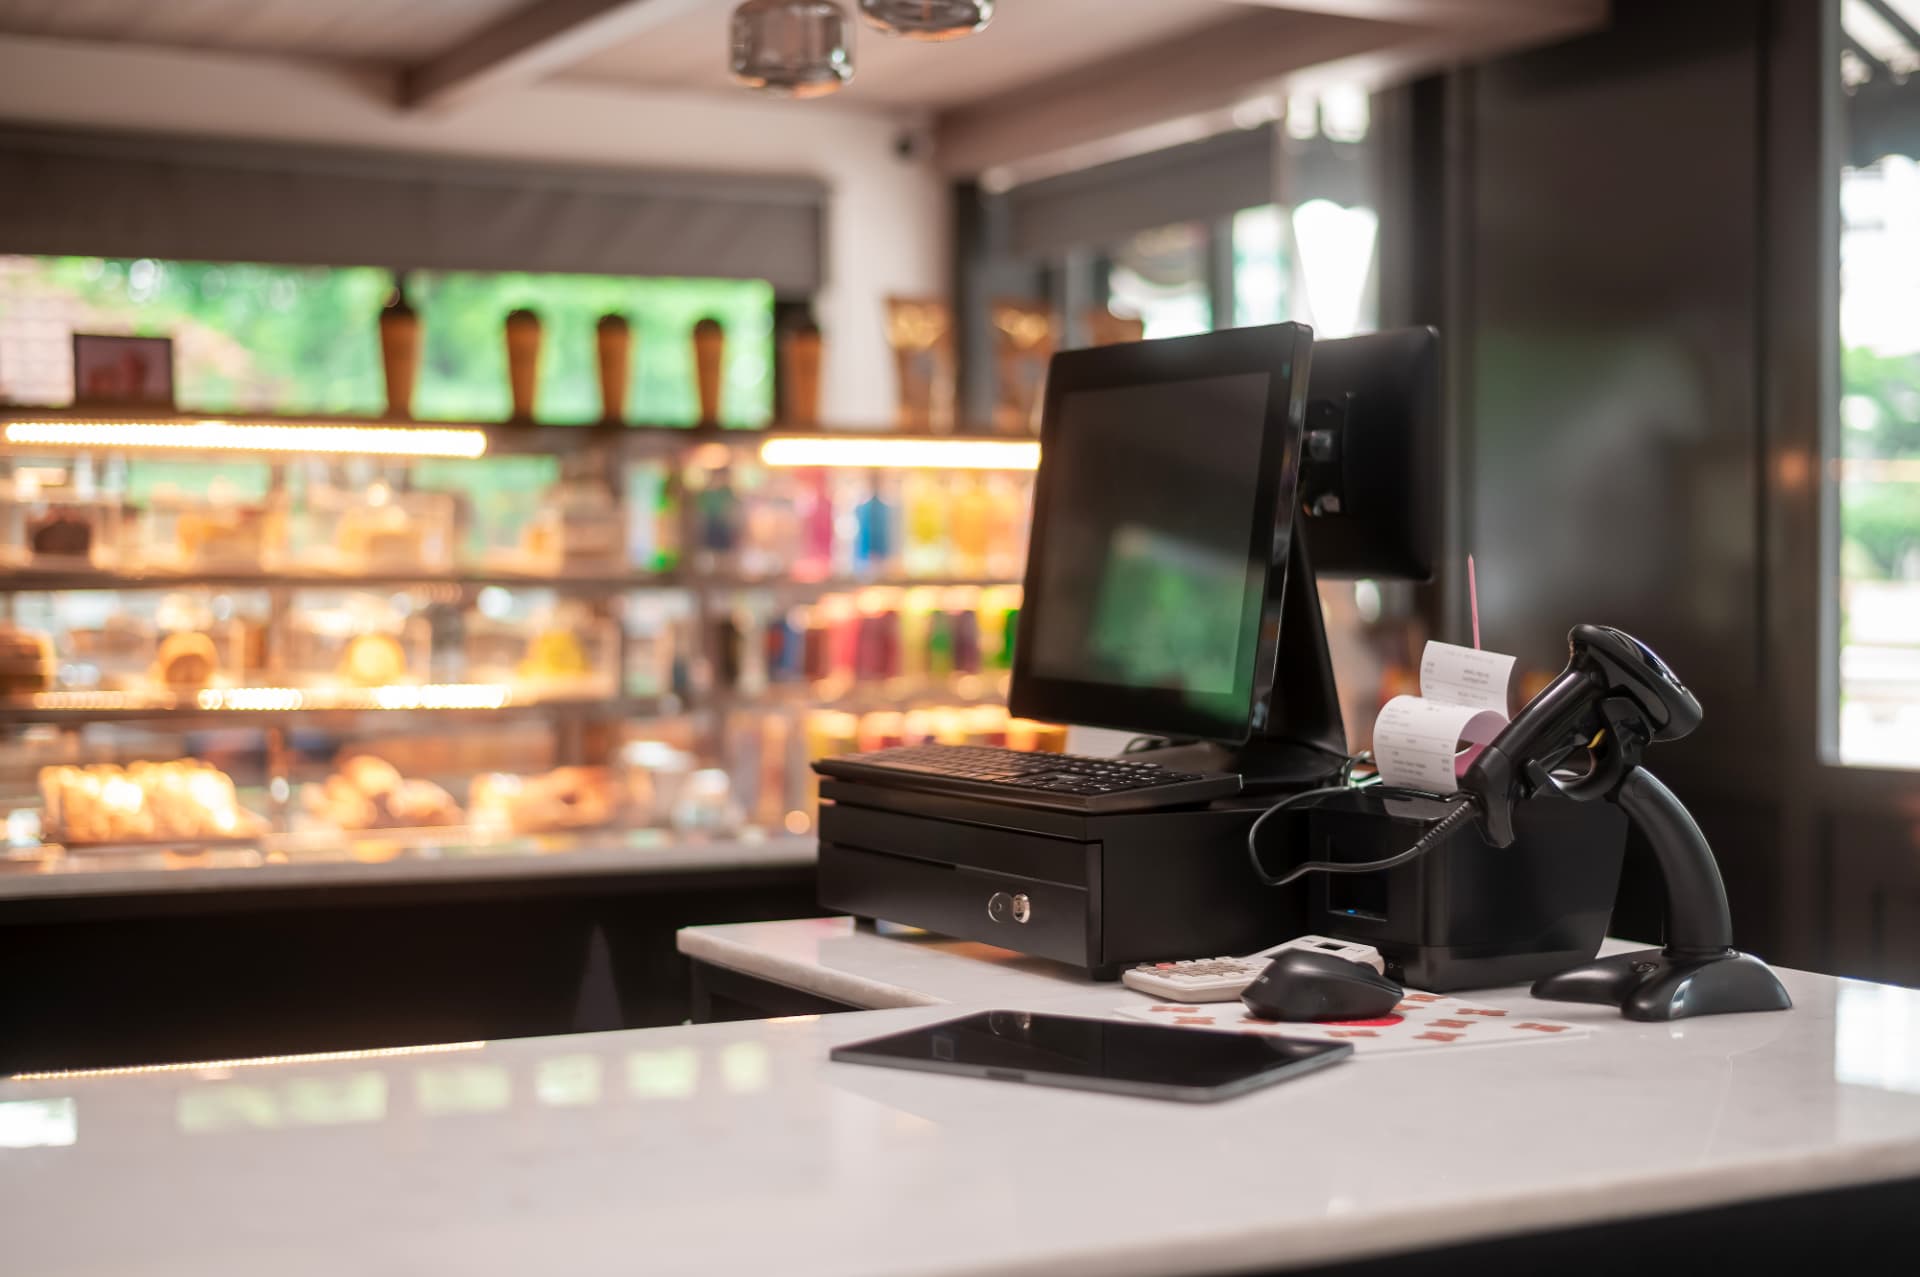
Choosing a payment processor is an important business decision because the provider you select can affect how easily customers pay, how clearly you understand your costs, and how well your payment setup supports your day-to-day operations.
The best payment processor is not necessarily the company advertising the lowest rate or the longest list of features. It is the provider that can support the way your business accepts payments today while giving you the flexibility to adjust as your needs change. If you are comparing payment processors, there are several factors worth evaluating before you make a decision.
What Does a Payment Processor Actually Do?
A payment processor helps move transaction information between your business, the customer's payment method, card networks, and financial institutions so a payment can be authorized and completed.
For merchants, payment processing is often part of a larger collection of services. Depending on your business, that can include payment terminals, point-of-sale technology, mobile payments, online payment gateways, virtual terminals, reporting tools, security features, and other merchant services. That is why comparing processors only by a quoted percentage can be misleading. You are choosing both a financial service and part of the technology your business may use every day.
Start With How Your Business Accepts Payments
Before comparing providers, take inventory of how your customers actually pay.
A neighborhood retailer that primarily accepts cards at a counter has different needs from a medical office that takes payments by phone. A restaurant may need fast in-person transactions and point-of-sale functionality, while an e-commerce company depends heavily on its online checkout experience.
Consider questions such as:
- Do customers primarily pay in person, online, over the phone, or through several channels?
- Do you need countertop terminals, mobile devices, or a full point-of-sale system?
- Do you operate from one location or several?
- Do you accept payments away from a fixed business location?
- Does your payment system need to connect with other business software?
- Are you planning to expand into additional locations or sales channels?
Answering these questions first makes it much easier to determine which provider and technology are appropriate for your business.
Understand the Full Cost of Processing
The processing rate matters, but it does not tell you the full cost of accepting payments. Depending on the provider and pricing model, your costs can include transaction fees, monthly charges, gateway fees, equipment costs, PCI-related fees, chargeback fees, and other account or service charges.
Ask prospective providers to explain how their pricing works in clear language. You should understand what you will pay, which fees can vary, and which charges are recurring. If the explanation is difficult to follow before you become a customer, that should factor into your decision.
Review the Contract, Not Just the Rate
Before signing an agreement, understand how long the contract lasts and what happens if you want to leave.
Questions worth asking include:
- Is there a fixed contract term?
- Does the agreement automatically renew?
- Is there an early termination fee?
- Is payment equipment purchased, rented, leased, or provided as part of the service?
- Are there additional agreements for gateways or other technology?
- What happens to your equipment or data if you change providers?
A competitive rate is less valuable if it comes with an agreement that does not fit your business.
Make Sure the Technology Fits Your Needs
Your processor should support the ways customers expect to pay. For an in-person business, that may mean EMV chip cards, contactless cards, or mobile wallets. For an e-commerce business, the quality and compatibility of the payment gateway may be more important.
Businesses operating across several channels should also consider how those systems work together. Managing completely separate platforms for online, mobile, and in-store payments can create additional administrative work. Instead of asking which provider has the most technology, ask which technology your business actually needs.
Ask About Security and PCI Compliance
Payment security should be part of every merchant's evaluation. The Payment Card Industry Data Security Standard, commonly called PCI DSS, establishes security requirements for organizations involved in accepting or processing payment card data. PCI requirements can still apply even when a merchant outsources much of its payment processing to a third party.
Ask potential providers how they support merchants with payment security and PCI compliance. You should also understand which responsibilities remain with your business. A provider can help simplify the process, but merchants should not assume that outsourcing payment processing removes every security responsibility.
Think About Integrations Before You Switch
Payment technology rarely operates in isolation. Your system may need to work with accounting software, an online store, scheduling tools, business management platforms, customer databases, or industry-specific software. Before changing processors, make a list of the systems your business depends on and ask whether the new solution will work with them. Discovering an integration problem after implementation can be expensive and disruptive.
Find Out What Support Looks Like
Customer support tends to feel unimportant when everything is working correctly. It becomes much more important when you cannot process a transaction, have a settlement question, need help with equipment, or do not understand something on your statement. Ask what support is available, how merchants access it, and who handles different types of problems.
A useful question is, "If I have a payment problem during normal business operations, what happens next?" The answer can tell you much more than a generic promise of great service.
Consider Where Your Business Is Going
The payment solution that works today should not become an unnecessary obstacle tomorrow. If you expect to add a second location, introduce online ordering, begin accepting mobile payments, expand into e-commerce, or change your business model, discuss those plans before choosing a provider. You do not need every possible feature immediately, but it is useful to know whether your payment environment can evolve without requiring you to start over.
A Practical Payment Processor Checklist
Before making your decision, make sure you can answer these questions:
- Does the provider support the ways my customers pay?
- Do I understand the pricing structure?
- Do I understand the contract?
- Will the technology work with my existing systems?
- Does the solution support appropriate payment security practices?
- Do I know how customer support works?
- Can the payment setup accommodate likely business growth?
- Do I feel confident asking this provider questions?
If several answers are unclear, keep evaluating your options.
The Right Processor Should Fit Your Business
There is no single payment processor that is automatically right for every merchant. A better approach is to start with your business model, customer experience, technology needs, and growth plans, then choose a provider that supports those priorities.
At Adara Group, we help merchants understand their payment options and identify solutions suited to how they actually do business.
Considering a new payment solution? Talk with Adara Group about your current setup and what you want it to do better.
Contact UsFrequently Asked Questions
What should I look for in a payment processor?
Look at the complete relationship, including pricing, contract terms, payment methods, equipment, integrations, security considerations, support, and the provider's ability to support your future needs.
Should I choose the processor with the lowest rate?
Not necessarily. A low advertised rate may not represent your total processing costs, and pricing is only one part of the decision. You should compare the entire fee structure and the services included.
Can I switch payment processors?
In many cases, yes, although your existing contract, equipment, gateway, or software integrations can affect the process. Review your current agreements before making a change.
Is PCI compliance the processor's responsibility?
Payment providers can handle important parts of the payment environment, but merchants can still have PCI DSS responsibilities. Your exact requirements depend on how you accept and manage payment data.